One onboarding. Then the program is yours.
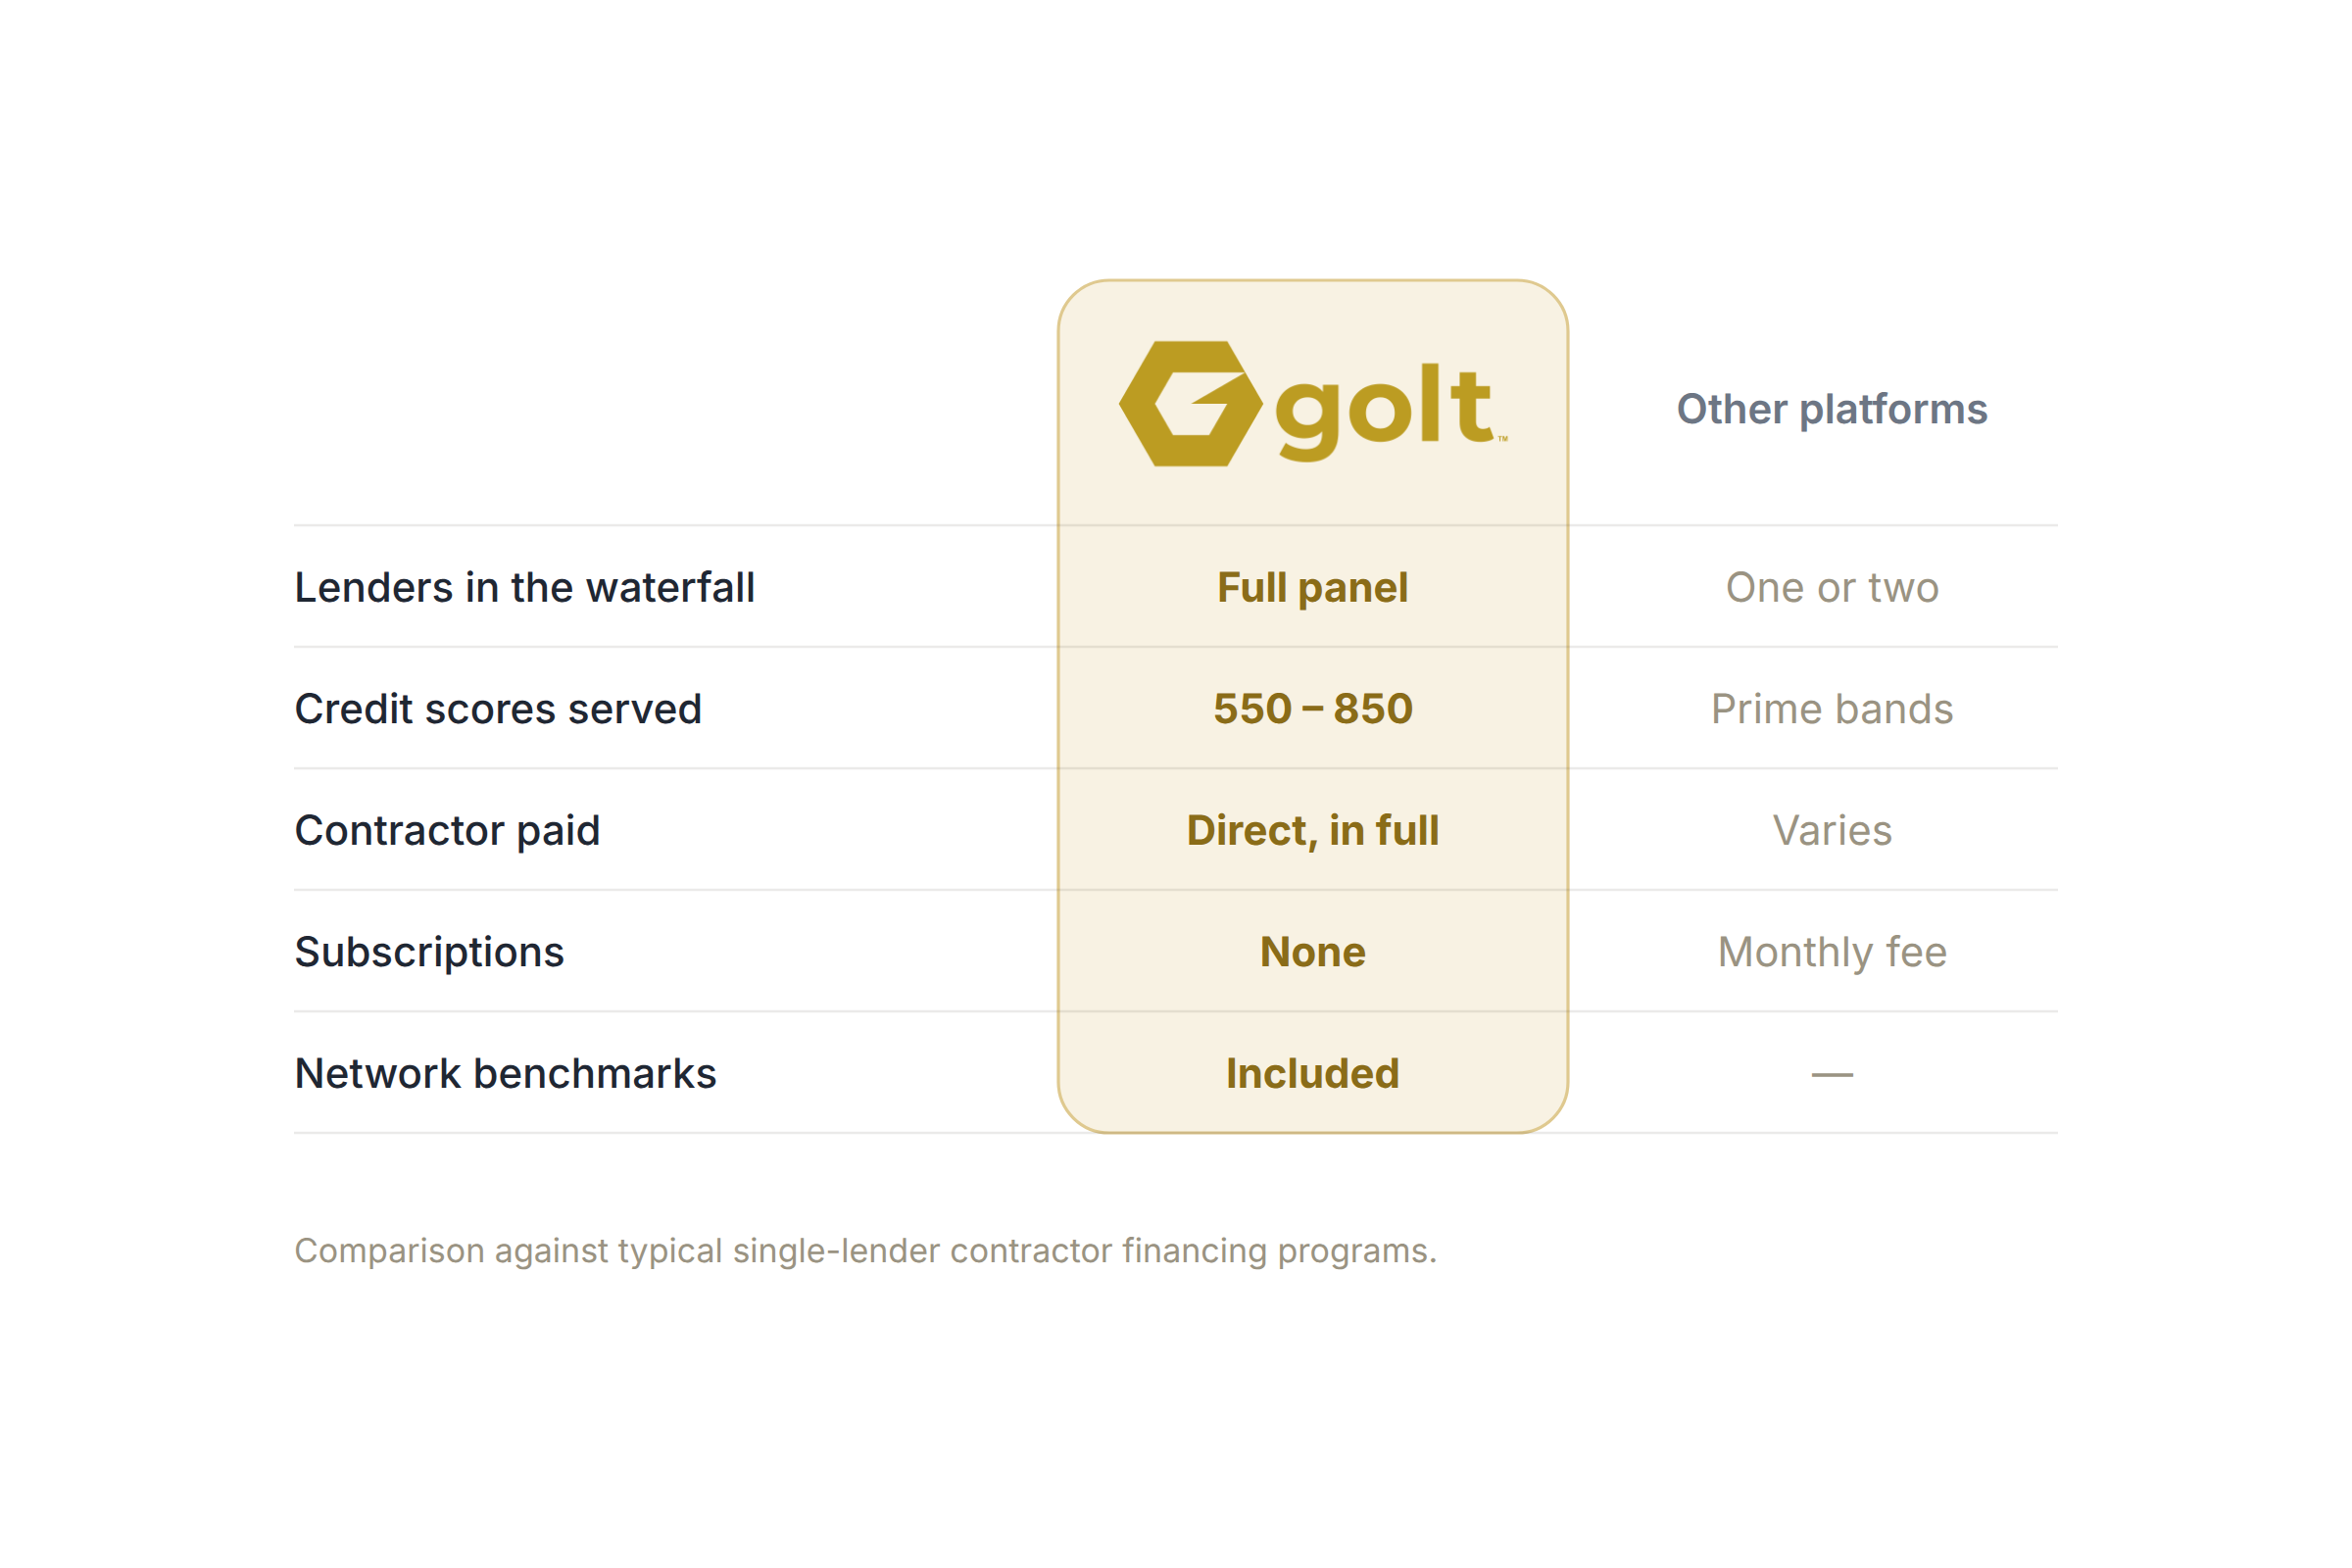
No subscription, no seat count, no annual renewal. Platform, training, and support for as long as you work with us — because we earn on the loans, not on your monthly bill.
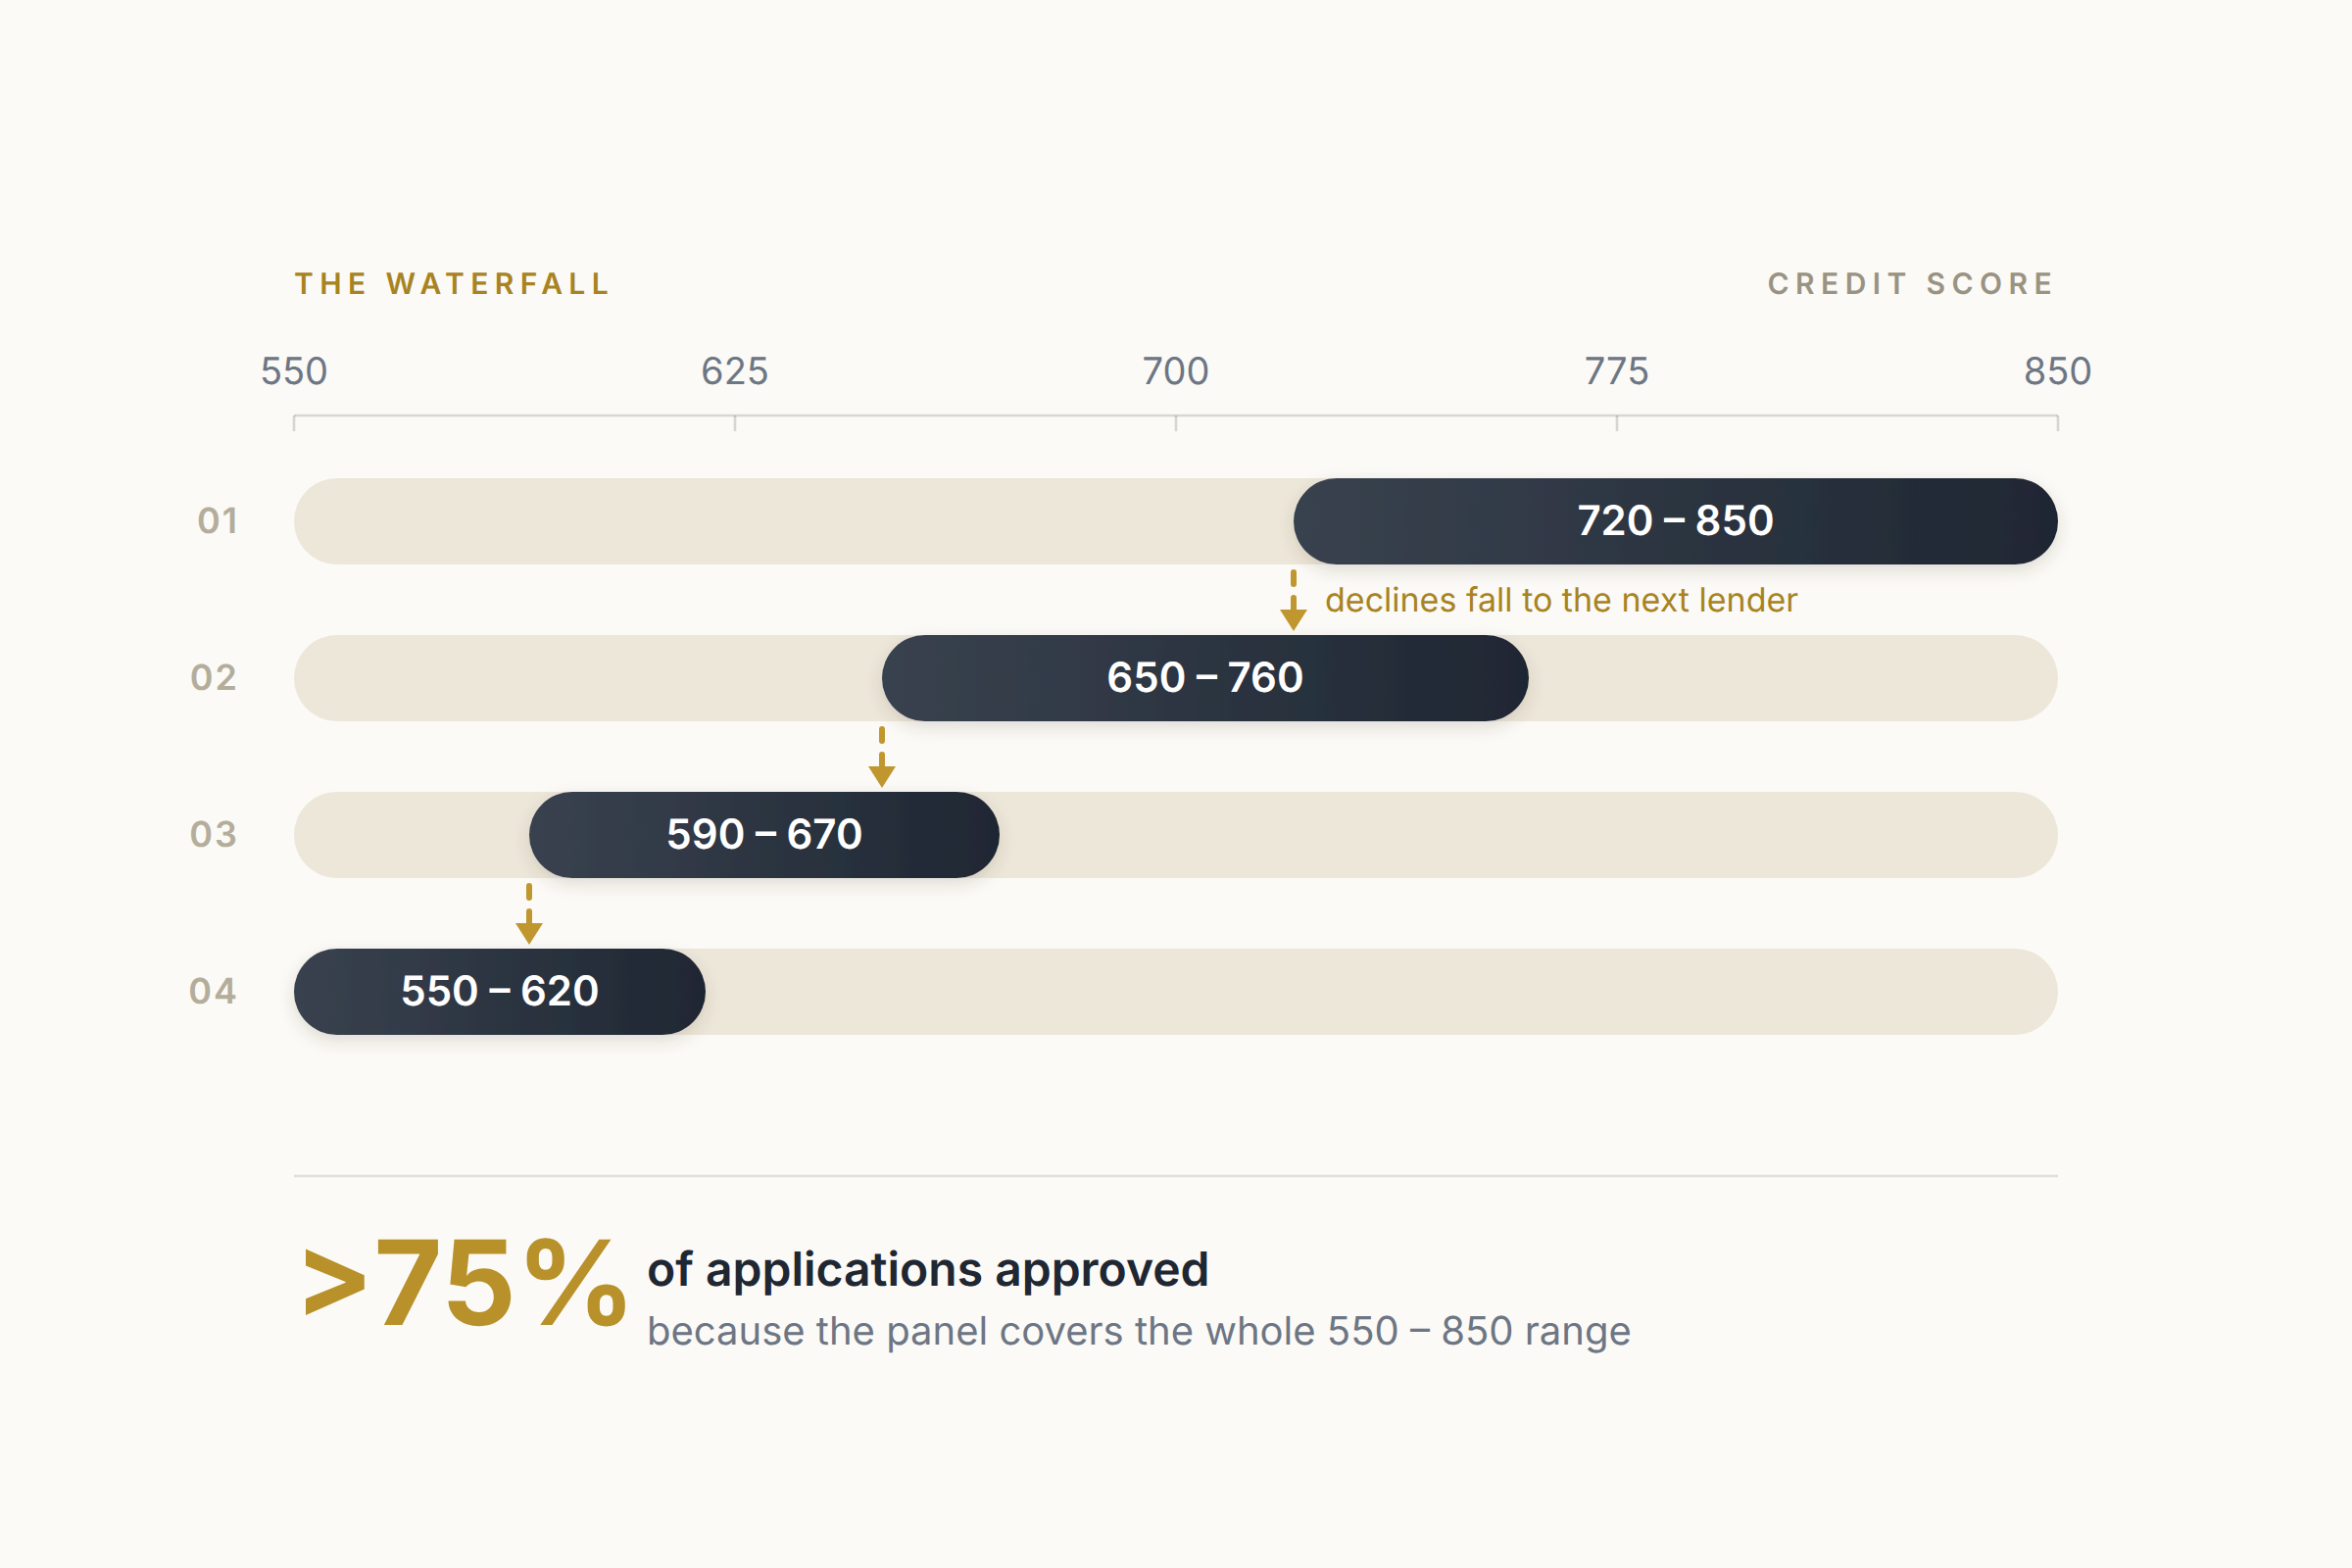
One application, the whole credit band
A decision in minutes with the payment options the homeowner qualifies for. Your rep stops guessing who is worth offering financing to, and stops shopping the customer around after a decline.
Present a payment
The monthly figure sits next to the price on every option quoted, not only the cheapest one.
Apply on the spot
A link, a QR code, or on-behalf entry. Checking options is a soft pull, so it costs nothing to look.
Get a real decision
Approval across 550 to 850 with the terms they qualify for, returned while you are still in the room.
We pay your company
Our lenders pay the contractor, never the homeowner, so the quote cannot be reshopped against you.
Find where you are today.
Jobs are dying on price and you want to start the right way rather than bolt a program on and hope the team uses it. We build the offer, train the people who sell, and stay on the calls until raising it is routine.
Every line, before you sign.
We earn on the loans, so we have no reason to bury a fee in the contract. Two things carry a cost, and we tell you both numbers before you offer anything.
One flat fee to get set up
It covers getting you approved with our lender and bank partners, building your account, training the people who sell, and lifetime access and support. You pay it once and never again.
Same-as-cash and deferred interest
These are the options with a fee to you. We quote it plainly so you can judge whether the close rate is worth it.
What every owner asks on the first call.
How fast is an approval?
Minutes. Your rep sends the homeowner a link or runs it on a tablet at the table, and the decision comes back while you are still standing in the kitchen, along with the payment options they qualify for.
Does applying hurt the homeowner's credit?
Checking options is a soft inquiry, so it does not affect their score. A hard pull only happens if they choose to move forward and finalize the loan.
Who receives the money?
You do. Every lender on our platform pays the contractor directly, so funds go to your company's account and never to the homeowner. That is deliberate: when the homeowner never touches the money, the job cannot be reshopped against your quote, and you are not chasing a customer for a balance after the work is done.
What does this cost us?
Standard loan options carry zero dealer fees, and there is no subscription. There is one onboarding fee, after which platform access, training, and support are yours for as long as you work with us. Promotional and deferred-interest plans do carry a fee, and we quote it plainly before you offer it.
What loan options are available?
Fixed-rate installment loans with APRs starting at 4.99% for qualified homeowners, across a range of terms so a rep can present a monthly payment that fits the ticket. We walk through the full option ladder and which ones to lead with on your consultation.
Can we offer promotional or deferred-interest plans?
Yes. Same-as-cash style and reduced-rate promotional plans are available where they help close bigger tickets. These are the options that carry a fee to you, so we help you decide when the higher close rate is worth it and when a standard loan is the better offer.
How long does onboarding take?
Most companies are live within days. We set up your account, train the people who sell, and hand your team the language that works. The first monthly call happens once real applications are coming through.
What happens if a customer is declined?
You still get an answer you can work with. Approval runs from 550 to 850, and when a file does not clear we tell your rep what would change it: a co-applicant, a different amount, or a smaller scope now.
Something not here? Ask us directly — we would rather answer it before you sign than after.
Tell us how you sell today.
Send this over and we come back with what we would expect your program to produce, and what it would take to get there. We do not quote an onboarding fee before we have seen your setup.